Article By Russ Choma
Elizabeth Warren decries the first family’s latest crypto play as a “clear conflict of interest and corruption.”
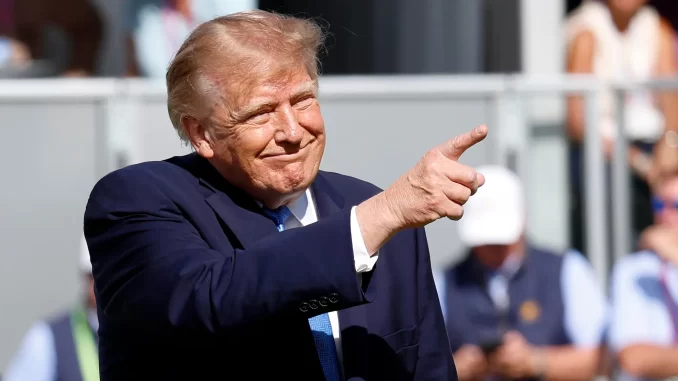
In a move that Sen. Elizabeth Warren has decried as a “clear conflict of interest and corruption,” one of the Trump Family’s most lucrative businesses is on its way to becoming a bank. And it’s set to be regulated by a government entity whose leader was appointed by, you guessed it…Donald Trump.
In August, the Office of the Comptroller of the Currency—one of three major bank regulators in the United States—declared that Donald Trump’s controversial crypto company, World Liberty Financial, could begin the process of establishing itself as a bank. It’s a complicated regulatory move that not only creates a new level of conflict of interest for the president and his family, but demonstrates just how drastically Trump has reshaped federal government policy in an effort to embrace his fellow crypto entrepreneurs.
The Trumps’ crypto odyssey ostensibly has roots in the family’s grievances surrounding the aftermath of the 2020 election. “I never thought I’d fall into the world of crypto until every bank began cancelling us for absolutely no reason other than the fact that my father was in politics,” Eric Trump told Fox News in 2024. “They came after us viciously. It wasn’t until that time that I realized how important crypto was.”
“We’ve been debanked. We’ve been deplatformed. We’ve had everything thrown at us with the kitchen sink.”
In reality, many big banks had long refused to do business with Donald Trump due to his past bankruptcies. But following the January 6, 2021, Capitol riot, some banks did, in fact, close Trump’s accounts with them. Trump and his sons founded World Liberty Financial in 2024, saying that it was needed because banks, and the whole system of banking regulation, had been so bad for their family. World Liberty Financial, they said, would be a “DeFi” company—decentralized finance. Instead of managing money through the stodgy old Wall Street system, it would allow people to do a lot of their financial activities on the blockchain.
“So you know, just very excited, entered the crypto space with this product, really looking to upend a lot of the traditional finance markets that we have viewed as very broken,” Donald Trump Jr. told an interviewer in October 2024, recounting how traditional banks turned away from the family after January 6. “We’ve gone through a lot in America. We’ve been debanked. We’ve been deplatformed. We’ve had everything thrown at us with the kitchen sink. And so we wanted to do something, to take on a system, frankly, that was quite broken.”
The company hasn’t done much of that—there is no way for the public to use World Liberty Financial for many of the activities traditionally performed by banks. But it has created a stablecoin, called USD1, which is a type of crypto asset designed to stay valued at $1. Stablecoins are useful as a way to move money between different crytpo currencies or between partners, without necessarily having to use actual US dollars, which are the common currency for most international transactions.
But, despite not doing much to actually take down the traditional banking world, the founding lore behind World Liberty’s creation makes its potential new status as a “national trust bank” an interesting turn of events. To be clear, the company will be no normal bank—it still won’t offer savings accounts, auto loans, credit cards, or ATMs. But for World Liberty, the development could be a goldmine.
Stablecoin companies make money by accepting US dollars in exchange for their stablecoin—$1 for one stablecoin—and then investing that real US currency in Treasury notes, reaping the interest as their profit. But since its launch, World Liberty has had to partner with an actual bank to hold onto that money for customers—which means it has had to split the profits. If World Liberty receives final approval to become a bank, it will be able to hold the money itself and keep all the profits.
So, why aren’t all crypto companies already established as banks? Because, in the past, it has taken a lot of work to become a bank. Speaking on the floor of the US Senate last week, Warren excoriated the decision by the OCC to grant World Liberty Financial a preliminary charter.
“Even setting aside the clear conflict of interest and corruption, World Liberty’s charter application would have been flatly denied under any previous administration, Republican or Democrat, due to its national security risks, anti-money laundering vulnerabilities, and lack of competent management,” Warren said.
The current Comptroller of the Currency, Jonathan V. Gould, was appointed last July by Trump, and he can be fired by Trump. Four other stable coin issuers have applied for, and received, at least conditional approval from the OCC to become banks—three of them since 2025. One crypto company received a conditional bank charter under the Biden administration, but its final approval was stalled until last December, when Trump’s OCC finally gave it the green light.
Hilary Allen, a banking law professor at American University, said that it’s impossible to say if the World Liberty application got literal special treatment because of its connection to the president, but the OCC’s turn towards allowing stabelcoin companies to become banks is a result of influence from above—influence which clearly has a self-interest.
“Before this OCC, I don’t think we would’ve seen these stablecoin national bank charters,” she says. “This wouldn’t have happened if Trump wasn’t setting things up to accommodate the crypto industry, which he was not just doing out of the goodness of his heart. They supported him, and also he has his own financial interest.”
Indeed, donors linked to the crypto industry gave heavily to back Trump during the 2024 election—and also contributed lavishly to celebrate Trump’s victory.
One of Allen’s concerns is that although neither the World Liberty Financial nor the other crypto banks will be backed by the FDIC—the federal government’s depositor insurer that guarantees you won’t lose your money if a bank fails—just being called a bank will offer the crypto companies an implied stamp of government approval and support. It’s a shot of credibility, but without some of the regulatory hurdles facing traditional banks.
“No regular person is going to say, ‘Hmm, a national trust charter doesn’t carry the same kind of insurance and regulation,’” Allen says.
World Liberty Financial is not yet a bank—it’s only received a preliminary approval, and now must raise a certain amount of money and jump through several more hoops before it can start operating. As part of its application process, World Liberty has already agreed to several changes. For instance, Eric Trump signed a passivity agreement, which prevents the Trump family from taking an active role in the daily management of the bank. Specifically, he agreed, among other things, that the Trumps would not have any management role, would not influence board decisions, and would not involve themselves with regulatory decisions.
According to the terms, the OCC itself will oversee and enforce Eric Trump’s promise that the Trumps wont get involved.
The OCC did not respond to a request for comment. But David Wachsman, a spokesperson for World Liberty Financial, said there were no conflicts of interest or special treatment given to the company as it applied for bank status.
“There are no conflicts of interest. We have made this very clear,” he said in an email. “There was no special treatment whatsoever and multiple direct competitors received approvals earlier and more rapidly than World Liberty. Approval is a comprehensive process led by OCC career staff.”
The passivity agreement, to one former regulator, who spoke on background as he now advises companies that are regulated by the OCC, is just window dressing. Eric Trump’s precise role at World Liberty Financial isn’t the problematic aspect. Even if he and his family aren’t actively running the bank, they still have a major financial interest in its profitability—and obvious access to the policy levers that impact the industry.
“The problem here is not the fact the Trumps are affiliated with a bank,” the former regulator said. “It’s the fact that Donald Trump can fire the bank regulator if the bank regulator doesn’t do what he says.”







Be the first to comment